If you have never been through a personal injury claim, the process can feel like a black box. You were hurt, an insurance company is involved, and eventually someone has to decide what the claim is worth. What happens in between is rarely explained.
A claim is not a single event. It is a process in which evidence, medical records, testimony and the parties' positions develop over time, and what looks straightforward in the first few days can look quite different months later. It also is not necessarily a fight all the way to trial. The useful mindset is to prepare for pushback, preserve the evidence, and understand the bigger picture before making important decisions.
Key Takeaways
- A claim does not necessarily end in trial. Settlement can happen before a lawsuit is filed or at almost any point during one.
- The claim is being evaluated from the first day, by the insurer, while you are still working out what happened.
- Property damage and injury are separate claims that move at different speeds.
- The medical record is more than a stack of bills. It is the main account of how the injury developed and what it has taken away.
- A recorded statement is not a friendly chat, and a deposition can be the turning point of a lawsuit.
- What you actually receive depends on costs, liens and fees, not just the size of a verdict or settlement.
- There is no universal timeline, and legal deadlines keep running while you negotiate.
How Do You File a Personal Injury Claim?
The phrase "filing a claim" means two different things, and mixing them up causes confusion.
An insurance claim begins when an insurer is notified of the accident. In a car accident, that is usually the at-fault driver's liability insurer (a third-party claim). It can also be your own insurer, for coverage such as collision, medical payments, or uninsured and underinsured motorist coverage (a first-party claim). Property damage and bodily injury are separate claims with separate timelines.
Who handles the claim. When the claim is reported, the insurer's intake team normally opens the file and assigns a claim number. Keep that number, because every call, letter and email about the claim will refer to it. The file is then assigned to an adjuster, which can take a day or two, so do not be alarmed if no one calls right away.
How the claim is staffed varies. Sometimes one adjuster handles the whole claim. Sometimes one adjuster handles the property damage and another handles the injury. If a lawsuit is filed, the claim is often transferred to a litigation adjuster, who may have more experience with contested cases.
Do not be surprised if different people are assigned as the claim moves along. Some insurers use a "team approach," which means no single adjuster owns the file and anyone on the team can handle a call. That can be frustrating, because each new voice on the phone has to read the notes in the file to get up to speed. It also means that what you say to one person becomes part of the file for everyone, which is one reason to be careful with early conversations. See Dealing With Insurance Companies.
Notifying an insurer is not the same as presenting the injury claim. The injury claim is usually presented after treatment has progressed far enough to show the injuries and their effects, which is often later than people expect.
A lawsuit is a separate step. If an insurance claim does not resolve, a complaint is filed in court. It must be filed within the statute of limitations, and claims against a public entity follow shorter rules. See California Filing Deadlines.
Most injury claims are resolved without a lawsuit, but the deadline keeps running while negotiations continue. A lawyer can handle the claim from the start or step in later. Do I Need a Personal Injury Lawyer? explains when that tends to help.
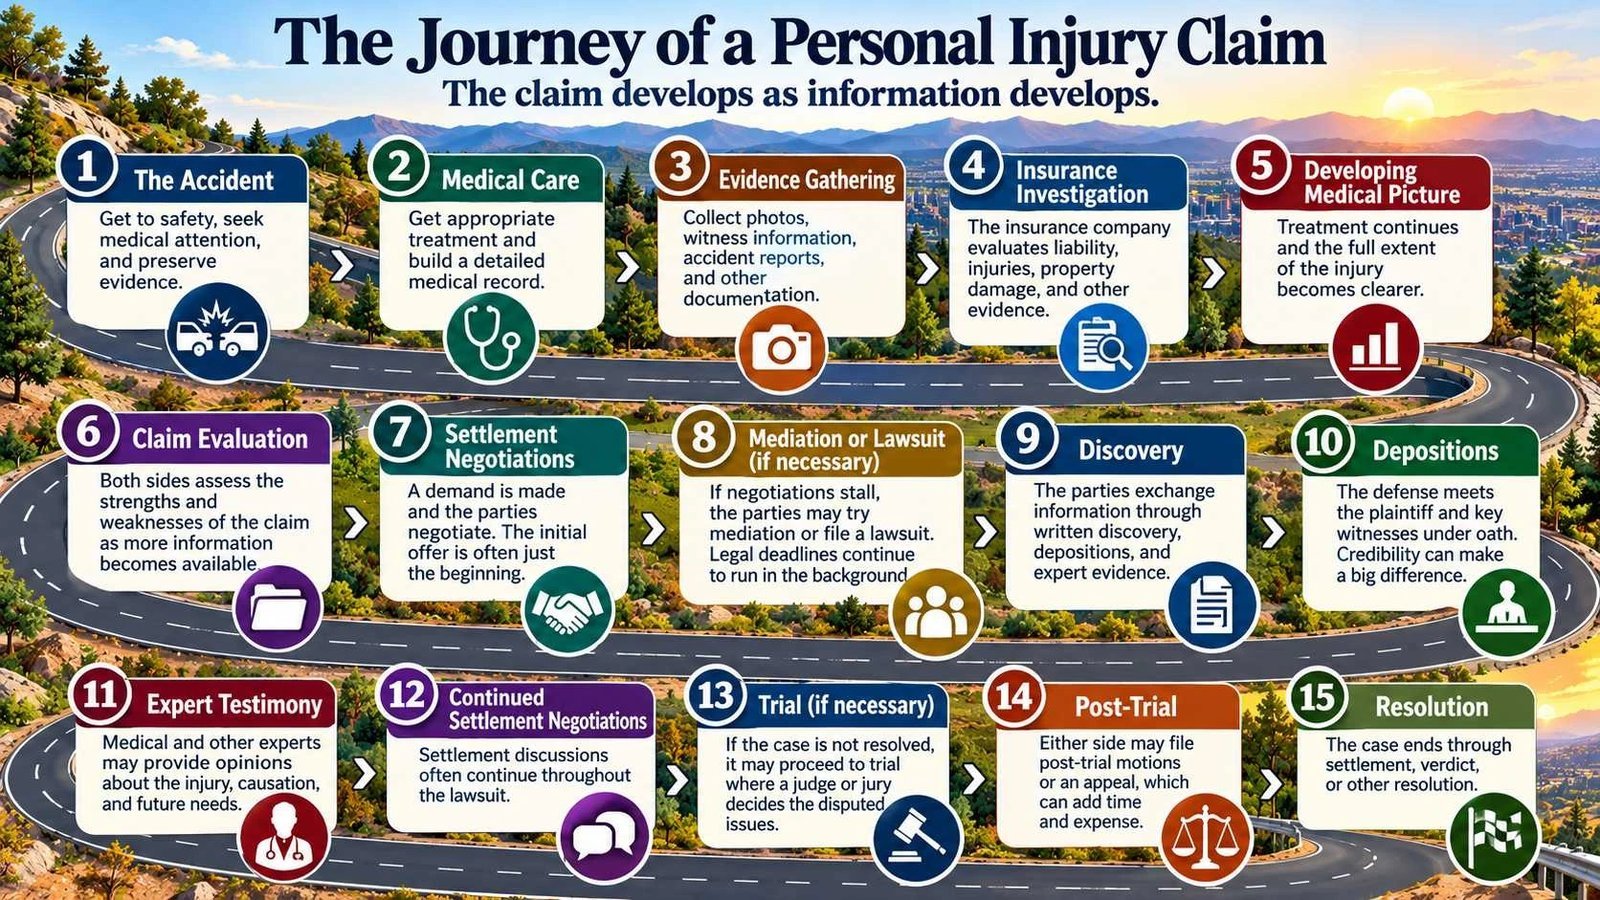
The Big Picture: How a Claim Develops
Every case is different, but most follow some version of this path. Not every claim travels through every stage.
Early
Accident, medical care, evidence gathering and the insurer's first investigation.
Middle
The medical picture becomes clearer, the claim is evaluated, and negotiations begin.
If needed
Mediation or a lawsuit, discovery, depositions, experts and continued settlement talks.
Resolution
Settlement at some stage, or trial and, sometimes, post-trial motions or an appeal.
A claim is better understood as a developing picture than a fixed number. Early on, many pieces are missing. As evidence and medical information accumulate, both sides see more clearly.
At the Scene: Protect Yourself and Preserve Evidence
Safety and medical attention come first. After that, the first hours and days produce evidence that can be hard to recreate later.
- Contact law enforcement where appropriate and exchange information
- Identify witnesses before they leave
- Photograph the vehicles, their positions, road conditions, traffic controls, lighting and any visible injuries
- Save dashcam or nearby surveillance footage before it is overwritten
Evidence preserved early is generally much easier to use than evidence someone remembers existed but can no longer find. The Immediate Steps and Evidence & Documentation guides go into more detail. The principle holds throughout the claim: document accurately, tell the truth, preserve evidence, think ahead.
A claim develops in stages, and not every case travels through all of them.
Property Damage and Injury Are Different Claims
Vehicle damage can usually be evaluated within weeks through photographs, estimates or a total-loss valuation. An injury cannot. Treatment, testing, therapy, injections or surgery may continue for months before its full extent is clear.
That is why an insurer may resolve the property damage while the injury claim stays open. A repaired car does not mean the injury claim is ready to settle. See Case Value for how the two interact.
Medical Treatment Builds the Record
Appropriate care comes first. At the same time, the records created during treatment become one of the foundations of the claim. They document diagnoses, symptoms, findings, treatment and whether the condition improved, persisted or worsened. They should also describe how the injury affects ordinary life: sleep, household tasks, work, caring for children, exercise.
Many people assume that anything true will automatically find its way into the chart. It often does not. A short intake form and a rushed appointment can leave an important limitation unrecorded. Keeping a short list of symptoms, limitations and questions before each visit, and sharing it with the provider, helps the record tell the truth completely. The aim is accuracy, never exaggeration.
TermWhen does treatment end? Maximum medical improvement
There is no rule that a claim must reach a particular number of treatment visits before it can be evaluated. You may hear the term maximum medical improvement (MMI): generally, a point at which the condition has stabilized and is not expected to improve substantially with more treatment. A person can reach MMI and still have symptoms or permanent limitations.
A stable medical point makes the consequences easier to evaluate. But treatment should follow medical need and professional recommendations, not a wish to increase a claim. See Getting Medical Care.
Meanwhile, the Insurance Company Is Evaluating the Claim
Once an insurer has notice, an adjuster generally begins investigating: the accident report, photographs, statements, witnesses, vehicle damage, medical records and bills, and wage loss. The insurer is looking at liability (who was responsible) and damages (what the injury has actually cost).
Third-party claim
A claim against the at-fault driver's liability insurer. That insurer evaluates the claim for its own insured and has its own financial interests. Do not assume it exists to help you obtain the maximum recovery.
First-party claim
A claim under your own policy, such as uninsured or underinsured motorist or medical-payments coverage. The relationship differs, and your insurer may owe contractual and good-faith duties depending on the coverage.
Adjusters look for weak points: conflicting statements, gaps in treatment, causation questions, pre-existing conditions, disputed liability, inconsistent records, or evidence the injury is less serious than claimed. That does not mean every adjuster acts improperly. It means the claim should be approached realistically. For more, see Dealing With Insurance Companies.
Your own words can end up in the file. Saying too much at the scene, describing the accident inaccurately or making casual comments about injuries can create problems later, and a recorded statement is not just a friendly conversation. Social media works the same way: a post that seems harmless can look very different in a disputed claim. Assume that important statements and evidence may eventually be read by someone whose job is to evaluate the claim critically.
DetailHow the claim strengthens or weakens as evidence develops
Escalating treatment, permanent limitations or a recommendation for future care can change an insurer's evaluation. But treatment alone does not make a claim more valuable. What matters is what the medical evidence shows about cause, seriousness, duration and future consequences.
Liability works the same way. A case that looks obvious can become complicated once photographs, witnesses or reconstruction are examined, and the reverse can happen too. The claim develops as information develops.
The Demand and the First Offer
At some point the available information may be organized into a settlement demand: what happened, why the other party is believed responsible, the injuries and treatment, the financial losses, and the compensation sought, supported by records, bills and photographs. A demand does not make a weak claim strong. Its effectiveness depends on the evidence behind it.
An insurer's first offer is often the start of a negotiation rather than the end. A useful question is how the insurer arrived at that number. The answer can reveal where the parties disagree: perhaps liability is accepted but the seriousness of the injury is disputed, or the treatment is called excessive, or future damages are viewed differently. Negotiations may involve several rounds. See Settlement Offers.
Time-Limited and Policy-Limits Demands
Insurance policy limits matter most when a claim's potential value exceeds the available liability coverage. California has specific statutory rules for certain pre-litigation time-limited demands: Code of Civil Procedure sections 999 through 999.5 set formal requirements for qualifying demands involving certain automobile, motor vehicle, homeowner and commercial premises liability policies. The framework took effect January 1, 2023, and addresses the form of the demand, the time allowed for acceptance, the settlement terms, the injuries claimed and reasonable proof.
A properly handled policy-limits demand can sometimes put real pressure on a liability insurer to resolve a claim within the limits. If an insurer rejects an appropriate opportunity to settle and its insured later faces a judgment above the limits, the insurer can potentially face exposure beyond the policy. This is informally called "opening the policy" or "popping the policy." It is not automatic: the demand's requirements, the insurer's circumstances and the applicable law all matter.
When Negotiations Stall
Mediation
A neutral helps each side assess strengths and weaknesses and look for a negotiated result. The mediator does not decide who wins.
Arbitration
An arbitrator hears evidence and arguments and decides. Whether it is binding depends on the circumstances and the governing agreement.
Litigation
A formal court process. Before filing simply because talks stalled, weigh the economics and risks carefully.
Litigation Changes the Nature of the Claim
Filing a lawsuit does not mean the case is going to trial. It means the dispute has entered a formal court process: complaint, service, response, discovery, motions, settlement discussions, mediation, and potentially trial.
Sometimes a lawsuit must be filed even while negotiations continue, because legal deadlines do not necessarily stop while the parties are talking. For many ordinary California personal injury claims, Code of Civil Procedure section 335.1 provides a general two-year statute of limitations for an action for injury to an individual caused by the wrongful act or neglect of another. That is not a universal deadline. Under Government Code section 911.2, a claim against a government entity relating to personal injury to a person or injury to personal property generally must be presented within six months after accrual, other deadlines can apply after a claim is rejected, and exceptions exist. Identify the applicable deadline early. The Filing Deadlines guide covers this in depth.
The complaint
Identifies the parties, describes the facts, states the legal claims and identifies the damages or relief sought. It is filed in a court with proper jurisdiction and venue.
Service of process
The defendant must be formally served, which provides legally recognized notice of the suit and a chance to respond.
The answer
The most common response. It addresses the allegations and may assert affirmative defenses.
A demurrer
Argues that, even assuming the pleaded facts are true, the complaint does not state a legally sufficient claim. It tests the pleading, not what happened at the accident.
Discovery: Where the Lawsuit Is Developed and Tested
Discovery is the formal exchange of information. Interrogatories require written answers under oath, requests for production obtain documents, and requests for admission narrow the issues truly in dispute. Written discovery is useful, but the answers are carefully prepared by attorneys and often do not change either side's evaluation much. Depositions can be different.
The Deposition: When the Defense Meets the Plaintiff
A deposition is questioning under oath, recorded by a court reporter. For the injured person it can be one of the most consequential moments in the case. The defense attorney may have spent months with a police report, photographs, records and bills. The deposition is often the first time that attorney sits across from the person behind the file. An adjuster may attend, though the defense attorney conducts the examination.
They are no longer evaluating only a file. They are meeting the person who may ultimately sit in front of a jury.
- Does the person answer questions directly?
- Can they explain what happened and how the injury changed their life?
- Are they consistent with the records and earlier statements?
- Do they come across as credible rather than evasive?
Plaintiff credibility and the overall impression a plaintiff makes are routinely weighed when judging how a case may play before a jury. When the facts can reasonably be viewed more than one way, credibility can tip the balance. That is why preparation matters, including practice questioning in appropriate cases. The goal is never to manufacture testimony. It is to tell the truth clearly and accurately, without being caught off guard by the process.
Also mattersDefendant depositions
The defendant's deposition can reveal how they remember the accident, what they knew, what they did before and after, and whether their account fits the other evidence. Sometimes it reinforces the defense position and sometimes it exposes weaknesses. Once witnesses are under oath and questioned carefully, the case may look different than it did on paper.
Expert Witnesses Can Change the Evaluation
Medical experts may address causation, prognosis, permanent injury or future treatment. Accident reconstruction or other technical experts may address how a collision occurred. Not every expert carries the same weight. A treating physician can be especially compelling because that doctor cared for the patient and was not hired solely to testify. What matters is the expert's relationship to the patient, the basis for the opinions, qualifications, methodology and any financial interest.
An expert can strengthen a case substantially or expose weaknesses. More experts do not automatically mean a stronger case.
Settlement Continues During the Lawsuit
A common misconception is that once a lawsuit is filed, settlement is off the table. Quite the opposite. Discussions can continue through discovery, after depositions, during mediation, after important motions, and even shortly before trial. Preparing for trial often gives both sides a clearer understanding of their risks. The objective is not to win the most arguments but to reach the best realistic outcome after weighing the evidence, risks, costs and what the client will actually receive.
Deciding Whether to Take a Case to Trial
The question is not simply whether the case is "good." Several practical factors drive the decision.
Venue
Where a case is tried can affect how a jury views certain claims and damages. A case strong on paper still has to persuade the particular jury that hears it.
Credibility
How will the plaintiff communicate? Which witnesses are believable? Are there inconsistencies the defense can exploit?
Costs
Depositions, experts, court reporting, jury fees, investigation and exhibits add up. An expert may be essential in one case and unnecessary, or even harmful, in another.
Formal offers
Code of Civil Procedure section 998 allows formal settlement offers during litigation. Rejecting a qualifying offer can carry significant cost consequences, which become part of the settle-or-try analysis.
Likely result
The question is not only what a jury could award, but how realistic that result is. A large gross value can still carry real risk.
Net to the client
Fees, costs, medical expenses and liens affect what the client keeps, and continuing treatment can add expenses. See Medical Bills & Liens.
This is one reason litigation should not be pursued simply because the other side will not pay the number first demanded. The potential benefit has to justify the added risk, expense and delay.
If the Case Goes to Trial, and After
A civil jury trial generally includes jury selection, opening statements, evidence, examination and cross-examination, closing arguments, jury instructions and deliberations. The pieces developed over months or years are finally presented to the people with authority to decide the disputed issues, and the jury decides under the law provided by the court.
A verdict does not necessarily end everything. Either side may file post-trial motions and may have a right to appeal. An appeal is not a second trial: the appellate court generally reviews the existing record for legal error, and new evidence is generally not introduced. It can add substantial time and expense to an already lengthy case.
How Long Does a Case Take?
There is no standard timeline. A claim with clear liability and an injury that resolves relatively quickly may settle within several months. A serious injury with extensive treatment, disputed liability, future medical needs or permanent impairment can take much longer, and litigation can extend the process to a year or more.
Length does not mean something has gone wrong. A serious injury often cannot be fairly evaluated until enough medical information exists. But delay should never become an excuse for ignoring deadlines: the clock can keep running while the claim is negotiated.
Preparing for Pushback
A useful mindset is to prepare for battle without assuming the battle will end in court. Preparation means having a plan: preserve evidence, obtain appropriate care, document what happened, understand the insurance coverage, identify weaknesses, and think several moves ahead.
It also means not being surprised when the other side disagrees. An insurer may dispute liability, question treatment, argue a bill is too high, blame a pre-existing condition, or make an offer that seems wholly inadequate. That does not necessarily mean something has gone wrong. Courthouses are full of people who disagree. The important step is to understand why the other side disagrees and whether the evidence supports your position.
The Claim Is a Puzzle
A claim is a collection of pieces that must fit together: the accident, liability, photographs and witnesses, property damage, medical records and treatment, lost income, future needs, permanent limitations, coverage, liens, experts and credibility. Some pieces are available immediately; others take months.
The objective is not to manufacture pieces that do not exist. It is to identify the pieces that are there, preserve and document them accurately, and understand what the complete picture shows. Rushing to settle before the picture is clear can be a mistake, and so can pursuing litigation only because the insurer will not agree with you.
The most useful question is often not "how much is my case worth?" but "what information do we have, what are we still missing, and how does it affect the next decision?" Several things happen at once in a claim: treatment continues while the insurer investigates, negotiations begin while evidence is gathered, and a lawsuit may be filed while talks continue. That is normal.
When Legal Guidance Becomes More Valuable
Not every claim requires an attorney. A straightforward claim with clear liability, limited injuries, adequate coverage and a cooperative insurer may be something a person can handle alone. Legal guidance tends to matter more in situations like these:
- The injury is serious or permanent
- Liability is disputed, or comparative fault is an issue
- Multiple parties are involved, or a government entity may be
- Significant treatment is needed and future damages are uncertain
- Insurance coverage is complicated, or substantial liens exist
- A significant settlement offer is difficult to evaluate
The point is not only whether a lawyer is involved but whether the person handling the claim understands what it is likely to look like several moves ahead. See Do I Need a Personal Injury Lawyer? and Fault and Liability.
Serving the Santa Clarita Valley
The process described here applies to accidents throughout the Santa Clarita Valley, including Santa Clarita, Valencia, Canyon Country, Newhall, Saugus, Stevenson Ranch and Castaic. When litigation becomes necessary, a case may involve the Los Angeles County Superior Court system, depending on the facts, jurisdiction and proper venue. For accident-specific detail, start with the Car Accidents guide, the FAQs or the Glossary.
The goal is not to assume the worst. It is to be prepared if the other side pushes back.
Frequently Asked Questions
Does every personal injury claim become a lawsuit?
No. A personal injury claim may be resolved through negotiations with the insurance company, mediation, arbitration, or another settlement process without a lawsuit reaching trial. If the parties cannot reach an agreement, litigation may become necessary.
How long does a personal injury claim take?
There is no standard timeline. A straightforward claim may resolve within several months, while a serious or disputed case involving extensive treatment or litigation can take a year or substantially longer.
Why can my car damage be resolved before my injury claim?
Property damage can often be evaluated relatively quickly through photographs, repair estimates, or a total-loss valuation. An injury may require months of treatment before its full extent and future consequences are understood.
What is the most important evidence in a personal injury claim?
There is no single piece of evidence that is always most important. Depending on the case, important evidence may include photographs, accident reports, witness testimony, medical records, property damage, employment records, expert opinions, and the testimony of the people involved.
Why can a deposition matter so much?
A deposition gives the defense an opportunity to question the injured person or another witness under oath. It can be the first time the defense attorney actually meets the person behind the medical records and other documents. Credibility, consistency, communication, and demeanor can all become important.
Can an insurance company use my statements against me?
Statements made during the claim process can become part of the evidence used to evaluate the claim. This is one reason it is important to be accurate, truthful, and careful when discussing an accident and injuries with an insurance company.
Is my own insurance company treated the same way as the other driver's insurance company?
No. A claim against the other driver's liability insurer is generally a third-party claim. A claim under your own policy, such as uninsured or underinsured motorist coverage, is a first-party claim and involves a different legal relationship. The duties owed by an insurer can therefore depend on the type of claim and the circumstances.
What happens if the insurance company denies my claim?
The answer depends in part on which insurance company is denying the claim and why. A third-party liability insurer may dispute liability, causation, damages, or other aspects of the claim. A first-party insurer may be denying coverage or benefits under the claimant's own policy. The reason for the denial matters, and depending on the circumstances, the dispute may continue through negotiation, mediation, arbitration, or litigation.
What is a time-limited demand?
A time-limited demand is a settlement offer made before a lawsuit or arbitration demand that gives a liability insurer a specified period to accept an offer to resolve a qualifying claim within policy limits. California Code of Civil Procedure sections 999 through 999.5 establish formal requirements for certain time-limited demands involving specified liability insurance policies.
What is maximum medical improvement?
MMI generally refers to a point at which a person's medical condition has stabilized and is not expected to substantially improve with additional treatment. It does not necessarily mean the person is symptom-free.
What is a California Code of Civil Procedure section 998 offer?
A section 998 offer is a formal settlement offer that can be made during litigation. Depending on the circumstances, rejecting an offer and failing to obtain a more favorable result can have significant consequences for litigation costs, including certain expert-witness costs. This can become an important factor when deciding whether continued litigation makes financial sense.
How long do I have to file a personal injury lawsuit in California?
For many ordinary California personal injury claims, Code of Civil Procedure section 335.1 provides a two-year statute of limitations for an action for injury to an individual caused by the wrongful act or neglect of another. Claims involving government entities are different. Government Code section 911.2 generally requires a claim relating to personal injury to a person or injury to personal property to be presented within six months after accrual, followed by additional requirements and deadlines that can apply depending on what happens to the claim.
Please remember that laws and regulations can change, and every legal situation is different. Information on this page is for general educational purposes and is not a substitute for legal advice about your particular circumstances.