Navigating Your Personal Injury Claim
Plain-English guidance on the rights and protections California law gives you after you've been hurt.
Start With the Step You're On
Each guide covers one stage of a claim in depth.
What to Do Right After an Accident
Immediate steps that protect both your health and your options, in the minutes and hours after it happens.
Read guide →Dealing With the Insurance Company
What you're required to say, what you're not, and why the first call matters more than people realize.
Read guide →Getting Medical Care
Learning about your medical care options, treatments, imaging, physical therapy and more.
Read guide →Fault and Liability in California
How California determines fault, and why being partly responsible doesn't mean you have no case.
Read guide →Evaluating the Settlement Offer
How to think through an offer, and why the timing of an offer matters as much as the number itself.
Read guide →California Filing Deadlines
The real time limits the law puts on your claim, including the exceptions that catch people off guard.
Read guide →Do You Need a Lawyer
An honest look at when legal help tends to matter most, and when it may not be necessary at all.
Read guide →Key Takeaways
- A personal injury claim usually cannot be fairly evaluated immediately after an accident because the full medical and factual picture has not developed.
- Insurance companies begin evaluating a claim early, often starting with the police report, photographs, witness information, and other available evidence.
- What you say and do after an accident can become part of the evidence later. Social media posts, photographs, statements, and gaps in treatment may all matter.
- Appropriate medical care is important, but simply accumulating large numbers of identical treatment visits does not necessarily make a claim stronger.
- Liability, medical treatment, medical records, lost income, property damage, credibility, insurance coverage, liens, and future consequences can all affect a claim.
- A settlement offer is not necessarily an indication of the full value of an injury claim, particularly while treatment is still ongoing.
- Before accepting a settlement, understand not only the gross amount but also what you may have to repay for medical bills, health insurance payments, liens, or other obligations.
- Even if you ultimately handle a claim yourself, an early consultation with an experienced personal injury attorney can help you understand the road ahead.
After an accident, it is natural to want answers immediately. How badly am I hurt? Who is responsible? What is my case worth? Should I talk to the insurance company? Should I accept the settlement offer?
The problem is that many of those questions cannot be answered accurately in the first few days. A personal injury claim develops over time, and important information often doesn't become available until the medical treatment, investigation, and recovery have had time to unfold.
You have to see the movie before you can review it.
Early in a claim, the injury, the recovery, and the insurance picture are all still being filmed.
The goal early in the process is not to predict the ending. It is to take each step carefully, document what is happening, get appropriate medical care, preserve evidence, and allow the picture to develop. By the time the credits are rolling, you should have a much better understanding of what happened, how you were affected, what your future looks like, and what the claim may actually be worth.
The Big Picture: Think of Your Claim as a Journey
A personal injury claim is more than proving that somebody else caused an accident. It is the process of putting together all the pieces needed to tell an accurate and credible story about what happened and how it affected you.
Those pieces can include the accident itself, the police report, photographs, witnesses, vehicle damage, medical treatment, medical records, diagnostic testing, lost income, insurance coverage, liens, your recovery, and any lasting problems. Some of those pieces may not even exist during the first few days after the accident.
That is why claims professionals often say that you have to see the movie before you can review it. Someone who asks two days after an accident whether to accept an early insurance offer is asking about a movie that has barely started. The characters aren't all known yet, the plot points haven't happened, there may be plot twists, and nobody knows how the movie ends.
The job during the early part of the claim is to help gather the information that will eventually allow the entire story to be evaluated.
What Happens After an Accident?
There is no single timeline that applies to every personal injury claim. A relatively minor injury may resolve quickly, while a serious injury can involve months or years of treatment and evaluation.
Generally, however, the process involves several overlapping stages:
Accident → Initial medical care → Investigation → Ongoing treatment → Re-evaluation → Understanding liability → Documenting damages → Evaluating the claim → Settlement negotiations → Lawsuit if necessary → Resolution
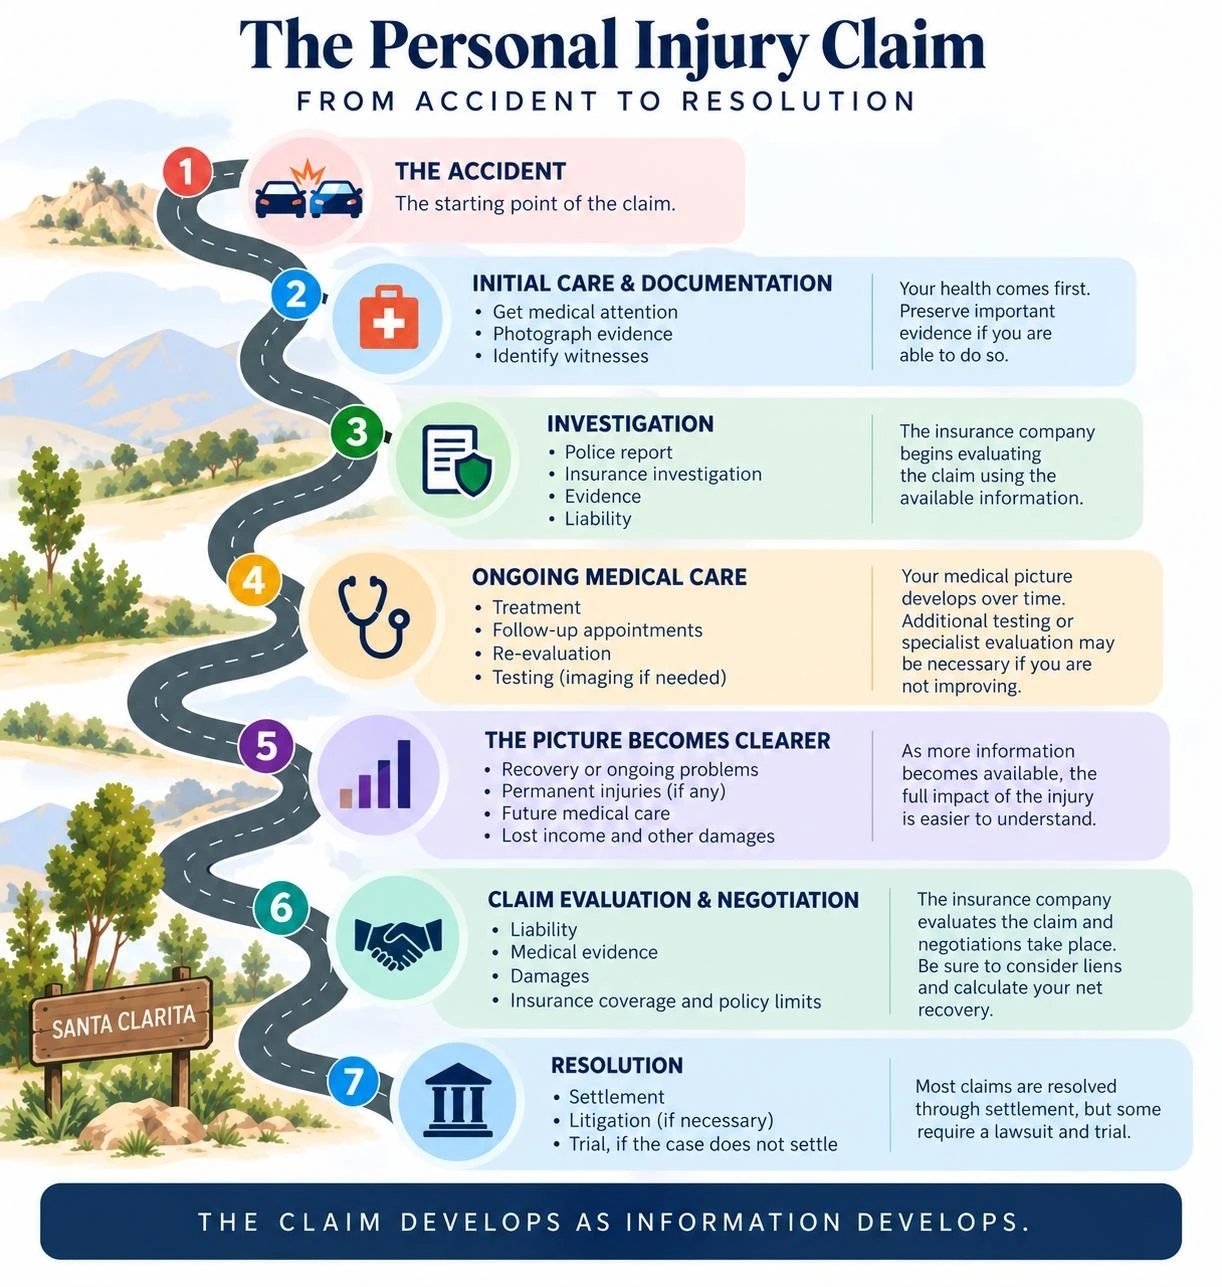
These stages are not always linear. New evidence can change the liability analysis. A medical examination can reveal an injury that wasn't initially apparent. A treatment gap may raise questions that need to be explained. A previously minor injury may turn out to be permanent.
The important point is that the claim develops as information develops.
1. Start by Getting the Important Things Right
The first few days after an accident can be chaotic. People are worried about their injuries, their vehicles, their jobs, their families, and what is going to happen next.
This is also the time when important evidence can be lost and statements can be made that later become significant. If you are physically able to do so, photographs of the accident scene, vehicles, visible injuries, road conditions, property damage, and other relevant evidence can be extremely valuable. Identifying witnesses and preserving video or other evidence may also matter. The Immediate Steps guide covers what to do in those first hours, and Evidence & Documentation explains what is worth keeping.
Just as importantly, be careful about what you say. There is usually little to be gained from announcing at the scene that you are going to sue someone, arguing with the other driver, or screaming at the police. Be courteous and factual. The accident is already stressful enough without creating additional evidence that may later become part of the story.
2. Get Appropriate Medical Care
Your health comes first. If you are injured, obtain appropriate medical attention and follow through with reasonable medical recommendations.
Good medical care is not about creating the largest possible stack of medical bills. It is about finding out what is actually wrong, treating the problem appropriately, monitoring your progress, and obtaining additional evaluation when the injury does not improve as expected.
A claim can become difficult to evaluate when someone receives the same treatment over and over without meaningful reassessment. On the other hand, a patient who initially receives conservative care and then requires imaging, specialist evaluation, injections, surgery, or other treatment because the problem has not resolved may have a very different medical story.
Think of the medical side of the claim as having chapters of its own. The initial evaluation is one chapter. Follow-up and treatment are another. Re-evaluation and additional testing may become another. Eventually, the medical story should tell you whether you recovered, whether you reached maximum medical improvement, or whether a permanent problem remains. More on this in Getting Medical Care.
Follow-up imaging and care and re-evaluation are part of the medical story an adjuster will eventually read.
3. The Insurance Company Is Evaluating the Claim Too
While you are recovering, the insurance company is also gathering information.
An adjuster will typically begin with information such as the police report, photographs, witness statements, vehicle damage, and other preliminary evidence. From that information, the adjuster begins developing a perception of the claim. That initial perception matters.
Depending on the circumstances, an adjuster may also look at publicly available information about the claimant, including social-media posts. A photograph or comment that seems harmless at the time can become problematic if it appears inconsistent with the claimed injuries.
For example, posting something immediately after an accident suggesting that you are completely fine may later be compared with medical records claiming significant ongoing symptoms. That does not necessarily mean the claim is false. But it can create a question that you will eventually have to answer.
Claims professionals know how often a casual post gets compared with the medical records later. The safest approach is simple: tell the truth, document accurately, and don't manufacture an image of yourself for social media that contradicts what you are telling your doctors or the insurance company.
For a closer look at the first call and what comes after it, see Dealing With Insurance Companies.
4. The Adjuster Is Forming a Valuation as the Claim Develops
Insurance companies commonly establish an internal reserve for a claim. In general terms, this is the insurer's working assessment of what the claim may ultimately cost.
A reserve is not a promise to pay you that amount, and it is not necessarily the final value of the claim. It is an internal valuation that can change when meaningful new information becomes available.
This is one reason it can be important for an attorney or an unrepresented claimant to keep the adjuster reasonably informed as the claim develops. If significant new medical information appears months into the claim, the adjuster may need to reconsider the earlier valuation.
The adjuster is also accountable to supervisors and the insurance company for the decisions being made. If the value of a claim suddenly increases dramatically at the end of the process, the adjuster may have to explain why the earlier evaluation did not change as the information developed.
That does not mean you should flood an adjuster with unnecessary information. It means that important developments should be documented and communicated appropriately as the claim progresses.
5. Determine Who Was Responsible
Liability is often an important early question, but it is not always as simple as identifying which driver received a citation.
The police report can be extremely important, particularly when it contains observations from the investigating officer and statements from independent witnesses. Photographs, vehicle damage, traffic signals, video, physical evidence, and witness testimony may also help establish what happened.
Certain types of accidents tend to raise familiar liability questions. A rear-end collision will often point toward responsibility for the driver who struck the vehicle ahead, although circumstances such as an unsafe lane change or another driver's conduct can change the analysis. Left-turn collisions present another common example where the circumstances surrounding the turn, speed, traffic signal, and conduct of the approaching vehicle may all matter.
California also recognizes comparative fault. In other words, more than one person can potentially bear responsibility for an accident. Fault and Liability explains how that works.
And there is another piece that people sometimes overlook: credibility. Eventually, someone may have to explain what happened to an insurance adjuster, opposing attorney, judge, or jury. The ability to tell the truth clearly and consistently matters. An attorney can help prepare you for the process, but no attorney can testify in your place about what you personally saw and experienced.
6. Document the Full Impact of the Injury
The value of a personal injury claim is not determined by a simple price list.
There is no chart that says a broken arm is worth a particular amount, a back injury is worth another amount, and a shoulder injury is worth something else. Two people can sustain seemingly similar injuries and have very different outcomes.
The evaluation may involve the nature and severity of the injury, objective medical findings, treatment, recovery, permanent impairment, pain, limitations on daily activities, lost income, future consequences, credibility, property damage, insurance coverage, and other factors.
This is also why medical records matter so much. If you consistently tell your doctors about your symptoms, follow appropriate recommendations, and the records document what you are experiencing, the medical history becomes part of the story that eventually supports the claim.
You should also preserve other evidence of how the injury affected your life. Photographs, employment records, calendars, correspondence, witness observations, and other documentation can help establish what happened and what changed afterward.
7. Understand How a Claim Is Eventually Valued
Once the medical picture is sufficiently developed, the claim can be evaluated more intelligently.
The economic portion may include things such as medical expenses and lost income. But in many personal injury cases, the more difficult question concerns non-economic damages: pain, suffering, inconvenience, emotional distress, loss of enjoyment of life, and the other ways an injury affects a person's life. There is no perfect mathematical formula for assigning a dollar amount to those losses.
If a case ultimately goes to trial and the parties cannot agree on a settlement, the jury is asked to make that judgment. Twelve people bring their own life experiences to the evidence and decide what they believe represents fair compensation under the law. Three frameworks are commonly used to think about it:
Framework 1The big-picture approach
What is the overall burden this injury has placed on someone's life? Did it last six months? A year? Ten years? Is there a permanent problem?
Framework 2The components approach
Consider the individual components of non-economic loss and evaluate them separately rather than treating the entire experience as one abstract number.
Framework 3The fair-trade approach
If someone had been warned before the accident that they were about to experience the pain, medical treatment, sleep problems, limitations, lost activities, and possible permanent consequences that actually occurred, what would represent a fair exchange for having to live through that experience?
None of these approaches produces a precise answer. They are frameworks for thinking about something that cannot be reduced to a simple mathematical formula. The Case Value page goes deeper into the factors involved.
8. Be Careful With Early Settlement Offers
One of the most common questions people ask is whether they should accept an early settlement. Again, remember the movie.
If you are still treating, you may not know whether you are going to make a full recovery. You may not know whether additional testing will be necessary. You may not know whether a seemingly minor injury will leave you with a permanent problem.
That does not mean an early settlement is always wrong. If you have recovered, feel fine, understand your situation, and the offer is reasonable, an early settlement may make sense. There can also be situations involving limited insurance coverage where accepting the available policy limits may be a rational decision even though the full medical picture is not yet known.
Before accepting any settlement, do the math. Subtract what is owed to providers, health plans, and other lienholders before deciding whether the offer works.
The settlement amount is not necessarily the amount you will put in your pocket. Medical providers may have outstanding balances. Health insurance companies may have reimbursement claims. Government programs such as Medicare or Medi-Cal may have rights that need to be addressed when applicable. Other liens or obligations may also affect the net recovery. Medical Bills & Liens explains how those work.
A small early offer can look very different once it is set beside a much larger stack of medical obligations that still need to be resolved. And once you sign a settlement agreement and release, you generally cannot come back later because the injury turned out to be worse than you expected. That is why understanding the entire picture before settling can be so important. See Evaluating the Settlement Offer.
9. Don't Lose Sight of the Deadline
California personal injury claims are subject to statutes of limitation and other deadlines. The applicable deadline can depend on the type of claim, who caused the injury, and whether a government entity is involved, among other factors.
Do not assume that because you are negotiating with an insurance company, the legal deadline has been extended. Insurance negotiations and statutory filing deadlines are two different things.
Some claims also involve special notice requirements that arise well before the ordinary statute of limitations. Government claims are one important example. If there is any question about a deadline, get legal advice rather than relying on an assumption. The California Filing Deadlines guide covers the details.
10. Do You Need a Lawyer?
Not every personal injury claim requires an attorney.
A straightforward accident involving minor injuries, clear liability, adequate insurance, and a quick recovery may be something a person can handle themselves. There is nothing inherently wrong with doing so.
Even then, however, there is considerable value in talking to an experienced personal injury attorney before deciding how to proceed. You don't have to hire the lawyer. You don't have to turn the claim over to a law firm. A consultation can simply give you a map of the territory.
Think of it like going river rafting. You may be capable of handling a simple stretch of river yourself, but if you have never been there before, it makes sense to look at the map before you launch the raft. You want to know where the difficult sections are, where the hazards are, and what is coming downstream.
The same principle applies to a personal injury claim. If the injury is serious, liability is disputed, there are multiple parties, substantial medical treatment is involved, you may have permanent injuries, insurance coverage is complicated, or there are significant liens or future damages to consider, professional advice can become much more valuable.
You are not required to build the entire house yourself simply because you are capable of putting up four walls and a roof. Sometimes the project is simple enough to handle yourself. Sometimes it is complicated enough that bringing in someone who understands the process saves you from expensive mistakes. Read more in Do You Need a Lawyer.
The Goal Is to Get the Whole Story Right
A personal injury claim is ultimately a story supported by evidence.
The accident is the beginning. The medical care tells part of what happened afterward. The records, photographs, witnesses, property damage, employment information, insurance coverage, and other evidence fill in the rest.
The job is not to make the story sound better than it was. It is to make sure the story is accurate, complete, and supported by the evidence.
That means documenting what happened. Getting appropriate medical care. Telling your doctors the truth. Preserving evidence. Being careful about statements and social media. Keeping track of important information. Understanding the insurance process. And thinking several moves ahead rather than making decisions based solely on what is happening today.
Frequently Asked Questions
How long does a personal injury claim take?
There is no standard timeline. A minor injury may resolve relatively quickly, while a serious injury requiring extensive treatment or involving permanent impairment can take much longer. The claim generally cannot be fairly evaluated until enough is known about the injury, recovery, damages, and insurance coverage.
Should I accept an insurance settlement while I am still treating?
Sometimes an early settlement can make sense, but it depends on the circumstances. If you are still treating, you may not yet know the full extent or future consequences of your injury. Before accepting an offer, consider whether your medical picture is sufficiently developed and determine what liens, reimbursement claims, medical bills, and other obligations will affect your actual net recovery.
What does an insurance adjuster look at when evaluating a claim?
An adjuster may consider the police report, photographs, witness statements, vehicle damage, medical records, treatment, diagnostic testing, statements by the claimant, lost income, insurance coverage, and other evidence. Depending on the circumstances, publicly available social-media information may also become part of the evaluation.
What is an insurance reserve?
A reserve is an insurer's internal working valuation of what a claim may ultimately cost. It is not a guaranteed settlement amount and can change when significant new information becomes available.
Why are photographs important after an accident?
Photographs can preserve evidence that may disappear over time. Depending on the accident, useful photographs can include the vehicles, property damage, accident scene, road conditions, visible injuries, and other physical evidence.
What if I was partly responsible for the accident?
California follows comparative-fault principles, meaning responsibility can potentially be divided among people whose conduct contributed to an accident. The specific effect depends on the facts and applicable law.
Do I have to hire a lawyer to make a personal injury claim?
No. Some straightforward claims can be handled without an attorney. However, even when you plan to handle the claim yourself, a consultation with an experienced personal injury attorney can help you understand the issues, deadlines, insurance coverage, potential damages, and problems you may encounter.
What if the insurance company offers me money shortly after the accident?
Be careful about treating an early offer as the final value of your claim. You may not yet know how serious the injury is or whether you will have permanent problems. If you are considering settlement, understand what rights you are giving up and calculate your likely net recovery after medical bills, liens, and reimbursement obligations.
What happens if I never fully recover?
If an injury leaves permanent problems, those future consequences may become an important part of the claim. The medical evidence should explain the nature of the residual condition, the expected future impact, and any reasonably supported future treatment or limitations.
When should I talk to a personal injury attorney?
There is no requirement that you wait until a problem develops. A consultation early in the process can help you understand what evidence to preserve, how to approach the insurance company, what medical issues may matter, and what deadlines apply. Legal guidance becomes particularly important when injuries are serious or permanent, liability is disputed, multiple parties are involved, insurance coverage is complicated, or substantial medical treatment and damages are involved.
Please remember that laws and regulations can change, and every legal situation is different. Information on this page is for general educational purposes and is not a substitute for legal advice about your particular circumstances.