Dealing With Insurance Companies
A clear-eyed look at who you are actually talking to, why they are calling, and how to handle each stage of the conversation.
The phone call usually arrives within a day or two of the accident. The voice is polite, the questions sound routine, and it can feel easier to just get it over with.
This guide is organized around that moment. It covers who is on the other end of the line, what they are really doing, and how to handle each stage of the conversation without being hostile or giving up more than you intended.
Jump to the part you need:
Key Takeaways
- The adjuster works for the insurance company, not for you, even when the call is friendly.
- Your injuries may not be clear for several days, so avoid committing to a complete account early.
- A recorded statement creates a permanent record that can be compared with your medical records and other evidence.
- Notify your own insurance company. Your policy may require it, and your own coverage may matter later.
- Collect the police report, photographs, medical records, witness information, and proof of lost income.
- Assume your statements, texts, and social-media posts may be reviewed.
- Signing a release generally ends your ability to seek more compensation for the released claims, so avoid rushing to settle.
- Medical evaluation and treatment come first. The claim can be addressed once your condition is clearer.
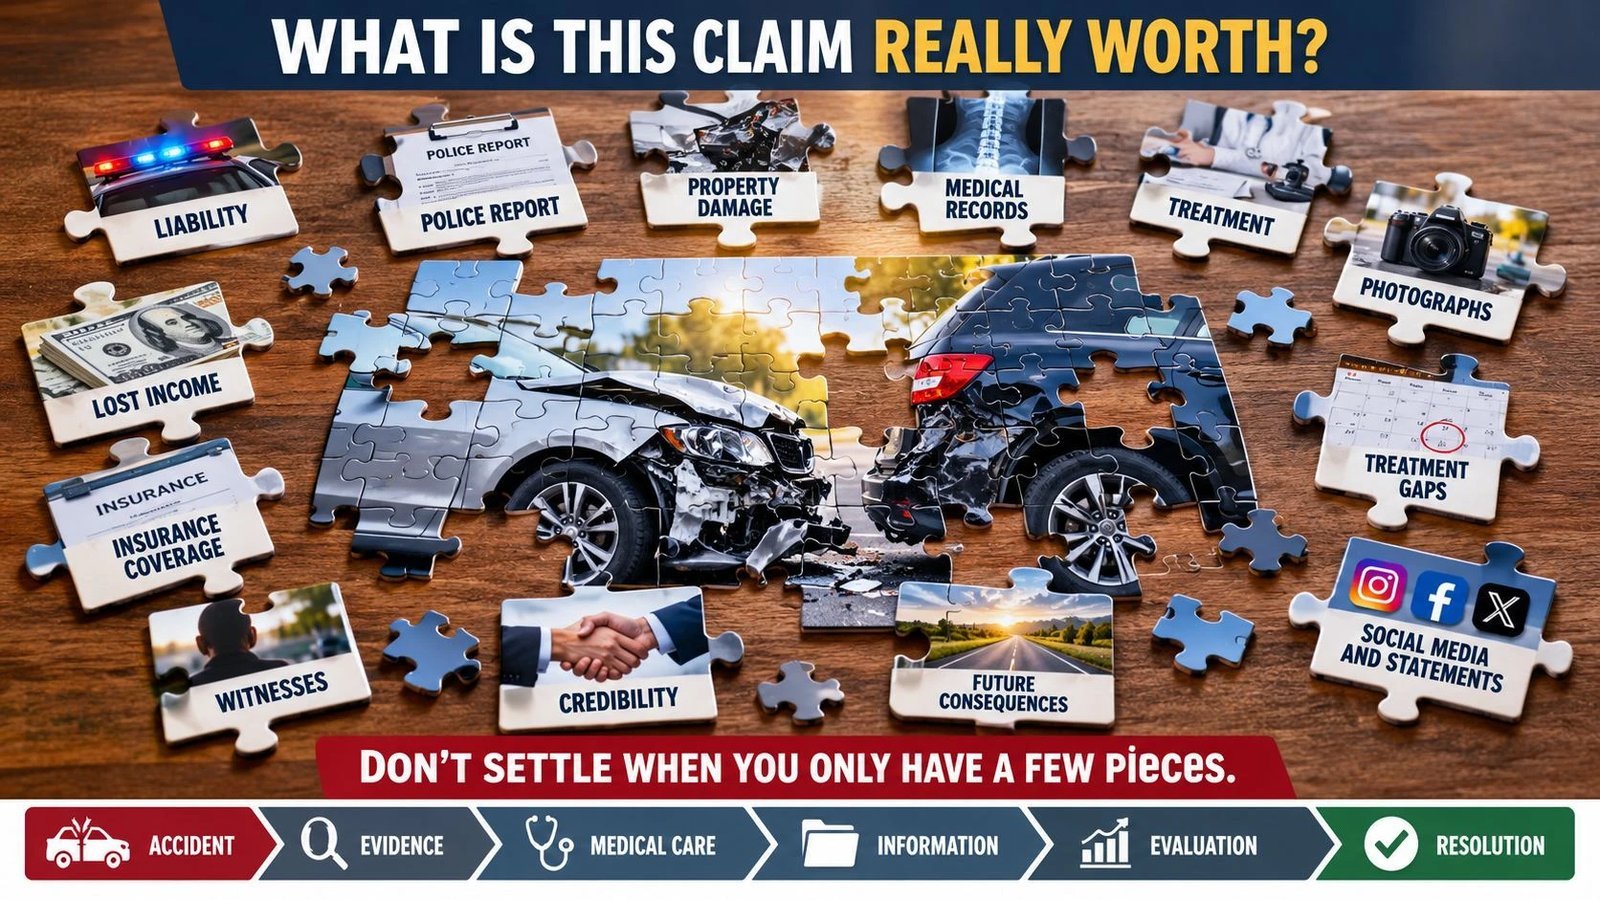
Who Is Actually Calling You
An insurance adjuster is a professional whose job is to investigate a claim and decide what the insurance company should pay. When the adjuster works for the other driver's insurer, the claim being investigated is one made against that insurer's own customer.
That is the whole relationship. The adjuster does not work for you, and the adjuster is not your personal representative, no matter how friendly the conversation feels.
Claims professionals often point out that the friendliest call is still a fact-gathering call. Courtesy and advocacy are different things, and only one of them is on your side.
None of this makes adjusters bad people. Most are polite and many are fair. It simply means you should understand whose interests the conversation serves before you decide what to say.
The first call usually comes within a day or two of the accident.
Why the Call Comes So Fast
The speed is not an accident. Early in a claim, details are fresh, injuries are uncertain, and the person on the phone has usually not yet talked to a doctor or an attorney.
From the insurer's side, that is a useful window. An early conversation can lock in a description of the accident, a description of how you feel, and a first impression of the claim that may be hard to change later.
You are not required to be unavailable. You are allowed to take a moment, collect your thoughts, and respond when you are ready.
Be Polite, Be Careful, Do Not Be Chatty
You do not need to treat the adjuster as an enemy. You also do not need to fill every silence. A short, courteous, factual conversation is usually better than a long, friendly one.
Generally fine to share
- Your name and contact information
- The date, time, and place of the accident
- The names of the vehicles and drivers involved
- Where the vehicle can be inspected, if it is damaged
Worth slowing down on
- Detailed descriptions of how the accident happened, especially speculation about speed, distance, or timing
- Your medical history, which can be requested through other channels once you understand what is being asked
- Your injuries, particularly if you have not yet been fully evaluated
- Anything you do not actually know
If you do not know an answer, say so. "I don't know" is better than a guess that turns out to be wrong.
A common defense-side observation: the most damaging statements are rarely lies. They are offhand guesses, such as "it happened so fast, I was probably going about the speed limit," that later get treated as facts.
What About a Recorded Statement?
Adjusters often ask whether they can record the conversation. The request is usually framed as routine, and sometimes it is.
A recorded statement becomes a permanent record of what you said at a point when you may not know the full extent of your injuries. Later, it can be compared against police reports, photographs, medical records, and witness accounts.
There is rarely a reason to give one right away. If the insurer insists, or you are not sure, it is reasonable to pause and get legal advice before agreeing. Whatever you decide, be truthful.
DetailQuestions to ask before agreeing to any recorded statement
- Why is the statement needed, and what will it be used for?
- Have I had a chance to be evaluated by a doctor?
- Do I understand the topics that will be covered?
- Would I like to speak with an attorney first?
You can also ask to respond in writing, or to have a short time to think. A reasonable adjuster will understand.
Your Own Insurance Company Is Different, to Some Extent
Your own insurer is in a different position from the other driver's insurer. You are its customer, your policy may require you to give prompt notice of an accident, and your coverage may become important.
That coverage can include collision, medical payments, rental car, and uninsured or underinsured motorist protection. Reporting the accident to your own insurer is generally a good idea, and the Immediate Steps guide covers the first things to do after a crash.
A word of caution: even with your own insurer, stick to accurate facts. Your policy may require cooperation, and the insurer may also be evaluating the claim from its own financial perspective, particularly on first-party coverages.
What the Insurance Company Is Looking At
An adjuster does not rely on any single piece of evidence. The evaluation builds from several sources, and the strongest claims tell the same story across all of them.
Source 1The police report
The report often shapes the adjuster's first impression of fault. It is important evidence, but it does not by itself decide civil liability. See Fault and Liability for how responsibility is actually determined.
Source 2Property damage
Photographs and repair estimates are used to understand the force of the collision. Minor damage does not automatically mean minor injury, but an insurer may compare the two. Preserve photographs of your vehicle before it is repaired, and see Car Accidents for more.
Source 3Medical treatment
Records show when you first reported symptoms, what you told providers, and what treatment followed. Delays and unexplained gaps in care can lead the insurer to question how serious the injury was. See Getting Medical Care.
Source 4Consistency
The adjuster compares what you said at the scene, in the first call, to your doctors, and online. Small differences are normal, since memory and symptoms change. Unexplained contradictions are what draw attention.
Adjusters build a file from many sources, and the strongest claims are consistent across all of them.
What You Say After the Accident Matters
Casual comments can take on a life of their own. "I'm fine" said to a bystander, a police officer, or a polite adjuster can later be placed next to medical records describing significant symptoms.
That does not mean the claim is false. Adrenaline, politeness, and the natural wish to downplay a problem all lead people to say "I'm okay" in the first hours. It does mean the comment may need to be explained later.
A more accurate response is often simply: "I'm not sure yet. I'm going to get checked out."
Social Media: Assume Someone Is Looking
Public posts, photographs, and comments can be reviewed. A photograph from a family outing, a workout check-in, or a cheerful update can look inconsistent with claimed limitations, even when the full context would explain it.
Injuries fluctuate, and having a good day does not mean you are not hurt. But a social-media snapshot is incomplete, and the other side may present it that way.
- Avoid posting about the accident, your injuries, or your physical activities while the claim is pending
- Do not delete existing posts without getting advice, since removing content can create separate problems
- Be thoughtful about what friends and family post and tag
- Check your privacy settings, but do not assume they make everything invisible
Adjusters and defense attorneys routinely search for a claimant's public online activity early in a claim and save what they find. Assume anything public is being saved.
Lost Wages Require Proof
If the injury caused you to miss work, the insurer will want evidence of the loss. Saying that you missed time is not the same as documenting it.
- Pay stubs from before and after the accident
- A note from your employer confirming dates missed and your rate of pay
- Doctor's notes restricting work or taking you off work
- Records for self-employment, such as invoices, bank deposits, and tax returns
- A simple log of dates and hours missed
The Evidence & Documentation page explains what is worth keeping and why.
Why Early Settlement Offers Deserve Caution
An early offer can look appealing. Bills are arriving, income may be down, and the insurer is presenting a way to make it all go away.
The question is not only whether the amount sounds like a lot. It is whether you yet know how serious the injury is, what treatment is ahead, and what you would be giving up.
A settlement typically involves signing a release. Once signed, it generally ends your ability to seek more compensation for the released claims, even if the injury later turns out to be worse.
That does not mean every early settlement is a mistake. A fully recovered person with a modest claim may reasonably accept a fair offer. The point is to decide with the full picture instead of reacting to a deadline that the insurer's call may have created.
The Settlement Offers guide goes into this in depth, and Medical Bills & Liens explains why the gross offer is not the same as what ends up in your pocket.
The Claim Is a Process, Not a Personal Battle
It is easy to take an insurance dispute personally, especially when you are hurt and the other side seems to be questioning your word.
It helps to see it as a process. The adjuster has a job to do, a supervisor to answer to, and a file that has to be justified. A disagreement over value or fault is usually business, not a judgment about your character.
Staying calm, factual, and consistent is almost always more effective than anger.
What Happens Behind the Scenes
You see the phone calls and the letters. You do not see the file.
Insurers commonly keep a running evaluation of each claim, often called a reserve, which is the company's internal working estimate of what the claim may ultimately cost. It is not a promise to pay any amount, and it changes as new information arrives. More on this in the Personal Injury Cases overview.
Adjusters answer to supervisors. If a claim's value jumps sharply late in the process, someone may ask why the earlier evaluation did not change as the information developed. Steady, documented updates make it easier for an adjuster to adjust.
This is one reason it matters to keep the adjuster reasonably informed about significant developments, such as a new diagnosis or a recommendation for further treatment. The point is not to overwhelm anyone with paperwork. It is to make sure the file reflects what is really happening.
Think Several Moves Ahead
Every statement you make now is one you may have to stand behind later. The aim is not to be guarded for its own sake. It is to avoid creating problems that are easy to avoid.
Before answering a question, it can help to ask yourself three things: Do I actually know this? Is this the right time to say it? Will I be comfortable with this answer in six months, next to my medical records?
What to Do After the Insurance Company Calls
- Write down the adjuster's name, company, phone number, and claim number
- Note the date, time, and what was discussed
- Keep every letter, email, and text in one place
- Do not sign anything you do not fully understand
- Report the accident to your own insurance company if you have not already
- Keep seeing your doctors, and keep records of symptoms and missed work
- Hold off on social-media posts about the accident or your activities
- Take your time before responding to any settlement offer
Do You Need a Lawyer to Deal With the Insurance Company?
Not always. A minor accident with little or no injury, clear fault, and straightforward property damage can often be handled directly.
The balance shifts when injuries are significant, fault is disputed, several parties are involved, coverage is limited or complicated, or a meaningful settlement offer is on the table. In those situations, an attorney who understands how adjusters evaluate claims can help you avoid avoidable mistakes.
Even if you plan to handle the claim yourself, a short consultation can give you a clearer map of what to expect. The Do I Need a Lawyer guide explains when legal help tends to matter most, and FAQs answers other common questions.
The Bottom Line
Dealing with an insurance company comes down to understanding the relationship. The adjuster is doing a job, and it is not your job to make that job easier at your own expense.
Be courteous. Be truthful. Do not guess, do not rush, and do not sign what you do not understand. Get medical care first, and let the picture of your injuries develop before you make big decisions.
If the claim is serious or complicated, or if something about the conversation makes you uneasy, that is a good time to get professional guidance. Deadlines also matter, so see Filing Deadlines as well.
Frequently Asked Questions
Should I talk to the other driver's insurance company?
You should generally be courteous and provide appropriate basic information, but you do not have to treat the other driver's insurer as though it were your representative. Be particularly cautious about giving a recorded statement or discussing the full extent of injuries before you understand them.
Should I give the insurance adjuster a recorded statement?
There is rarely a reason to rush into a recorded statement immediately after an accident. A recording creates a permanent record of your words that can later be compared with your medical records and other evidence. If the insurer insists on a statement or you are unsure how to respond, consider getting legal advice first.
Should I call my own insurance company after an accident?
Generally, yes. Your policy may require prompt notice and cooperation. Your own insurance may also become important if the other driver has insufficient insurance, has no insurance, or if you need to make a collision claim. California's Department of Insurance recommends promptly notifying your insurer.
Why does the insurance adjuster want to talk to me so quickly?
The insurer wants to begin investigating the accident while information is fresh. The adjuster may be gathering information about liability, property damage, witnesses, injuries, and other aspects of the claim. An early conversation can also shape the insurer's initial understanding of the case.
What should I say if the adjuster asks how I am feeling?
Tell the truth. If you do not yet know the full extent of your injuries, say so. You might explain that you are experiencing pain and seeking medical care to determine the nature and extent of your injuries. Avoid saying "I'm fine" merely as a social courtesy if that is not an accurate description. "I'm fine" can be used against you later.
Can the insurance company look at my social media?
Publicly available social-media material may be reviewed during an insurance claim. Photographs, videos, comments, and posts that appear inconsistent with claimed injuries can create questions about the claim. The safest course is generally not to post about the accident, your injuries, or your physical activities while the claim is being evaluated.
Why does vehicle damage matter in an injury claim?
Property damage can provide physical evidence about the collision. Adjusters may compare the amount and location of vehicle damage with the claimed mechanism of injury. It is not a rule that minor vehicle damage means minor injuries, but significant differences between the physical evidence and claimed injuries can lead to additional questions.
Why are gaps in medical treatment a problem?
An insurer may view significant gaps in treatment as evidence that an injury was less serious than claimed, particularly when there is no explanation for the gap. Sometimes there is a perfectly legitimate reason for interrupted treatment. The important thing is to follow appropriate medical care and be able to explain accurately what happened.
Should I accept an early settlement offer?
Do not assume that an early offer is necessarily adequate simply because it is offered quickly. Before accepting a settlement, you should understand your injuries, future treatment, medical bills, liens or reimbursement claims, lost income, and what rights you are giving up by signing a release.
Do I need a lawyer to deal with an insurance company?
Not necessarily. A straightforward claim involving minor injuries and clear liability may be manageable without an attorney. Legal guidance becomes more valuable as the injuries, liability issues, insurance coverage, medical treatment, financial losses, or settlement issues become more complicated.
Please remember that laws and regulations can change, and every legal situation is different. Information on this page is for general educational purposes and is not a substitute for legal advice about your particular circumstances.